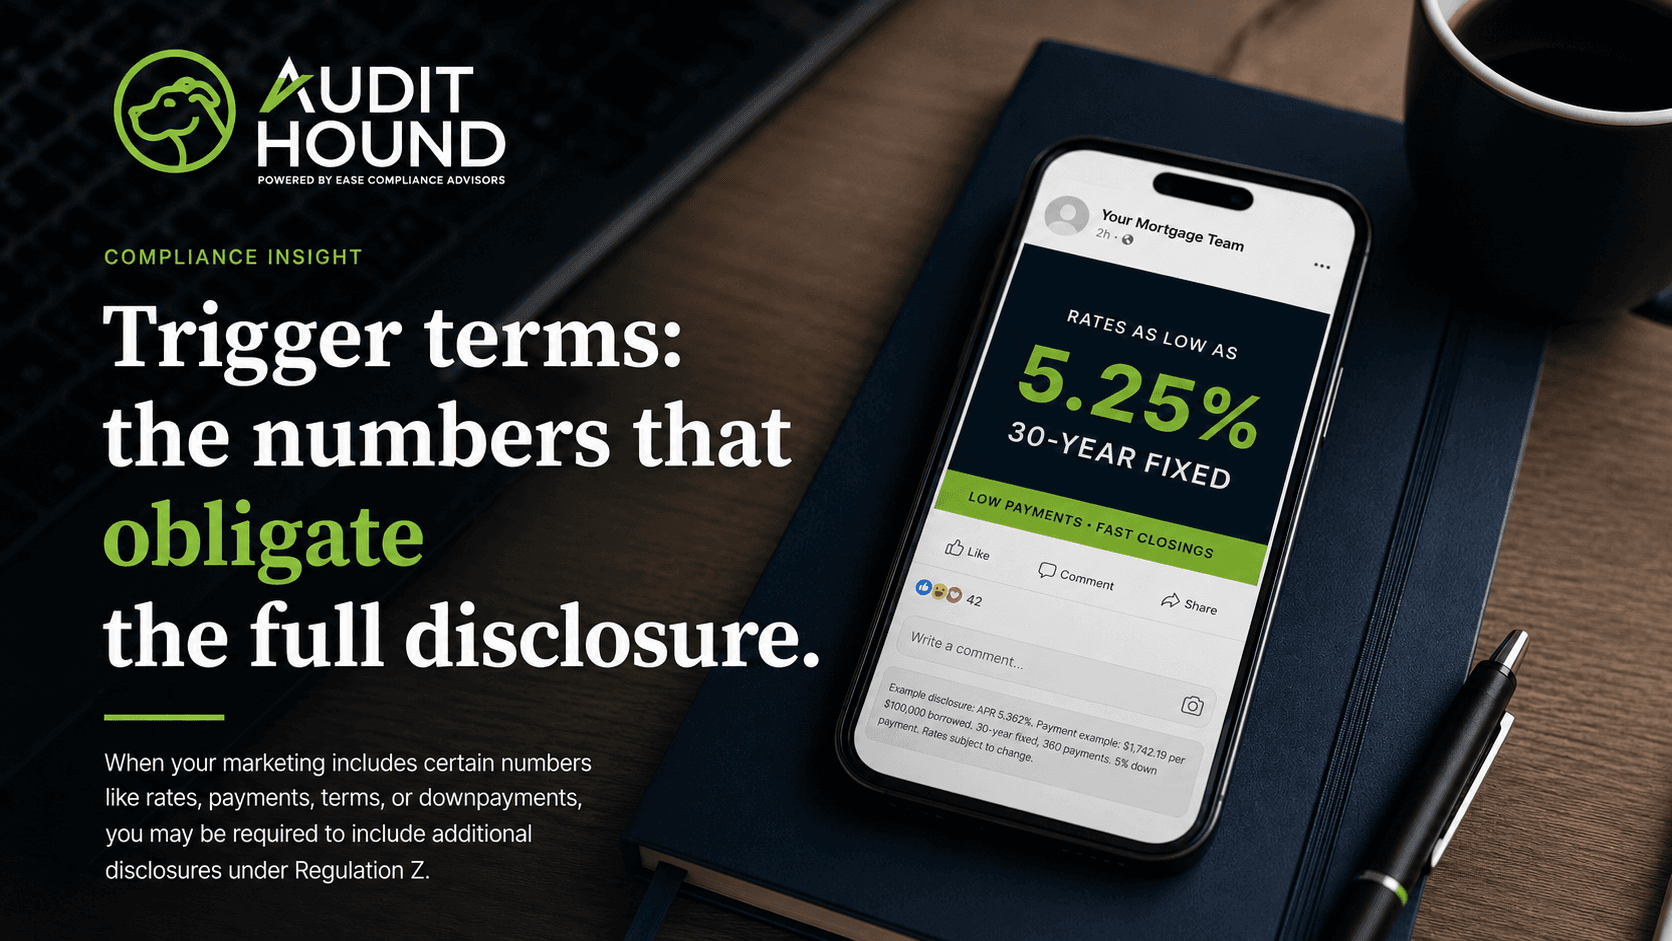
Here is the short version: the moment an ad states certain specific numbers, Regulation Z stops treating it as branding and starts treating it as a credit offer. The ad then owes the reader a defined set of additional disclosures. Most trigger-term findings are not about bad intent. They are about a rate or payment typed into a post by someone who did not know the number carried obligations.
The terms that trigger
For closed-end credit, Regulation Z (12 CFR 1026.24(d)) lists the triggering terms. In plain language, an ad triggers when it states any of the following:
- The amount or percentage of any downpayment.
- The number of payments or the period of repayment.
- The amount of any payment.
- The amount of any finance charge.
A specific payment amount ("$1,850 a month"), a term ("30-year"), or a downpayment ("only 3 percent down") each does it. General statements that do not state the specific terms, for example "great rates" or "flexible terms", do not trigger the additional disclosures, though they still have to be accurate and not misleading.
What the ad then owes
Once a triggering term appears, the ad must also clearly and conspicuously state the amount or percentage of the downpayment, the terms of repayment over the full term of the loan, and the annual percentage rate, using that term or the abbreviation APR, plus a note if the rate may increase. A rate on its own carries a related rule: if an ad states a simple rate of interest, Regulation Z (12 CFR 1026.24(c)) requires the APR at least as prominently.
Where officers get caught
The pattern we confirm most often in monitoring is the rate graphic: a flyer or image with a bold rate and term, attached to a short caption. The disclosures cannot live in a comment or behind a link. Text inside images is advertising, and regulators read it the way any consumer would. Video carries the same weight: a spoken "lock five and a quarter on a thirty year" triggers exactly as print does.
The second pattern is the vanished disclosure. The original post carried the full block; an officer later re-shares the image alone, and the new post stands bare. Every re-post is its own advertisement.
What good practice looks like
- Treat any specific number in marketing as a flag for review before it posts.
- Put required disclosures inside the creative, not in captions or comments.
- Review video by transcript, not by thumbnail.
- Keep the ad, with its disclosures, in your marketing file as published.
Audit Hound reviews every post, image, and video transcript against the trigger-term rules automatically, and an EASE compliance advisor confirms each finding before your team sees it.
This article is compliance reference material, not legal advice. Rules change and states differ; confirm requirements for your licenses with your compliance advisor or counsel.