Social media compliance for mortgage teams.
Audit Hound reviews your loan officers' full social presence, profiles and every post, against federal rules and each licensed state's advertising requirements, then an EASE compliance advisor signs off before you see the report.
What we review on social
We review the profile and About sections and every post, across the platforms your loan officers use. Every item is checked against the complete rulebook: the required marketing elements (company name and NMLS ID, company license and regulator information, location, contact details, a link to NMLS Consumer Access, Equal Housing Opportunity, accurate licensed states, and the loan officer's name, NMLS ID, and license information) and, far beyond that:
Every post, watched and scored
The portal shows the whole posting picture: weekly volume by platform, the flagged trend, and every flagged post with its violation, filterable by platform and date. The screen below is the live product with a fictional team.
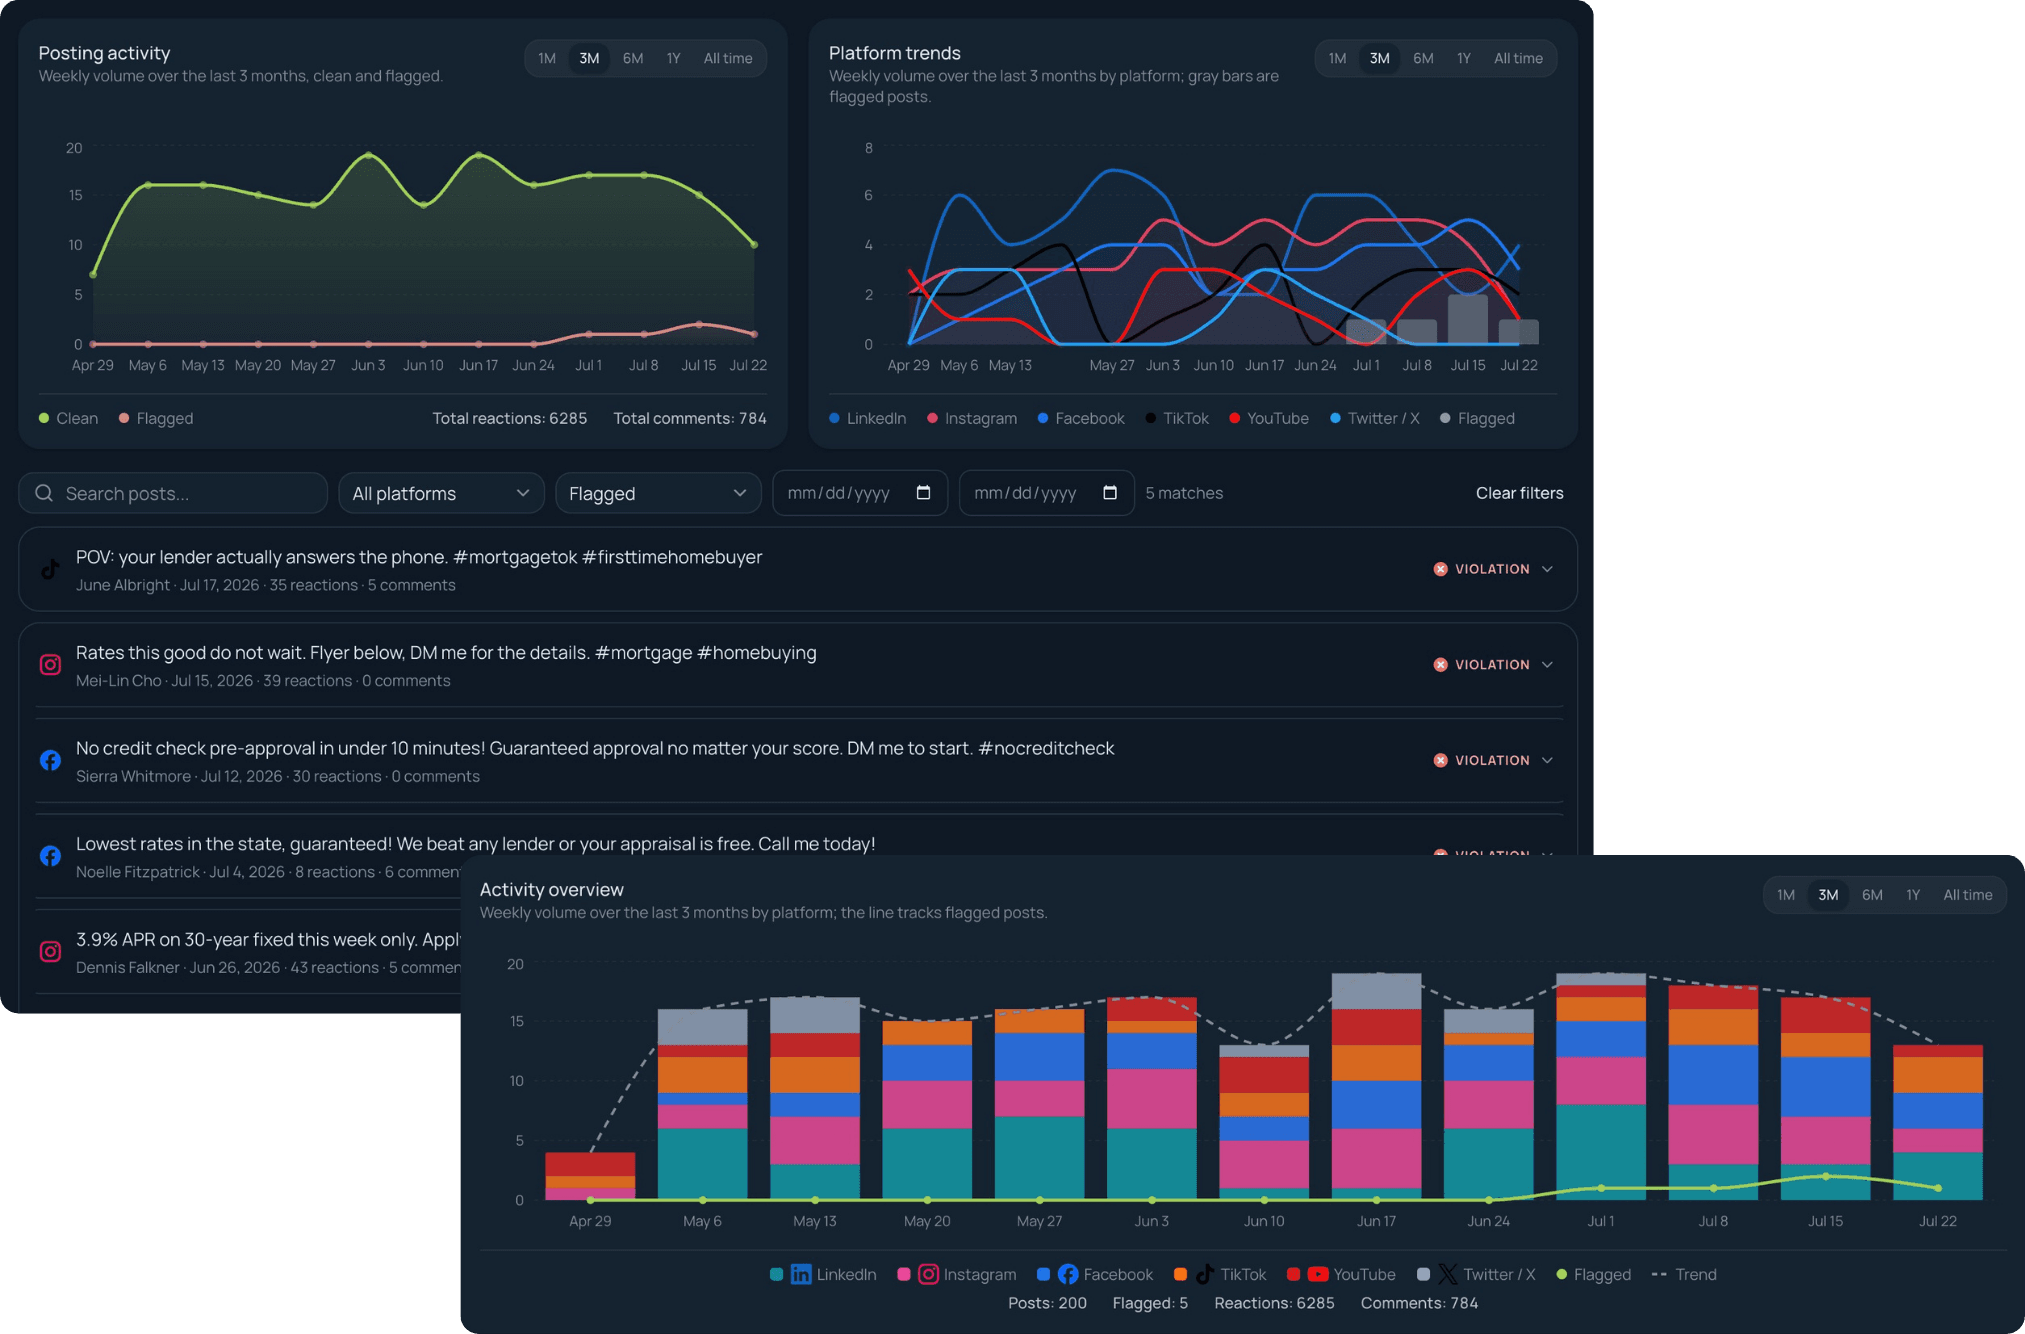
Social findings, with the evidence in the report
The violations regulators cite most are in the image, not the caption. The captured post appears in the report next to the rule it breaks. Fictional samples below.
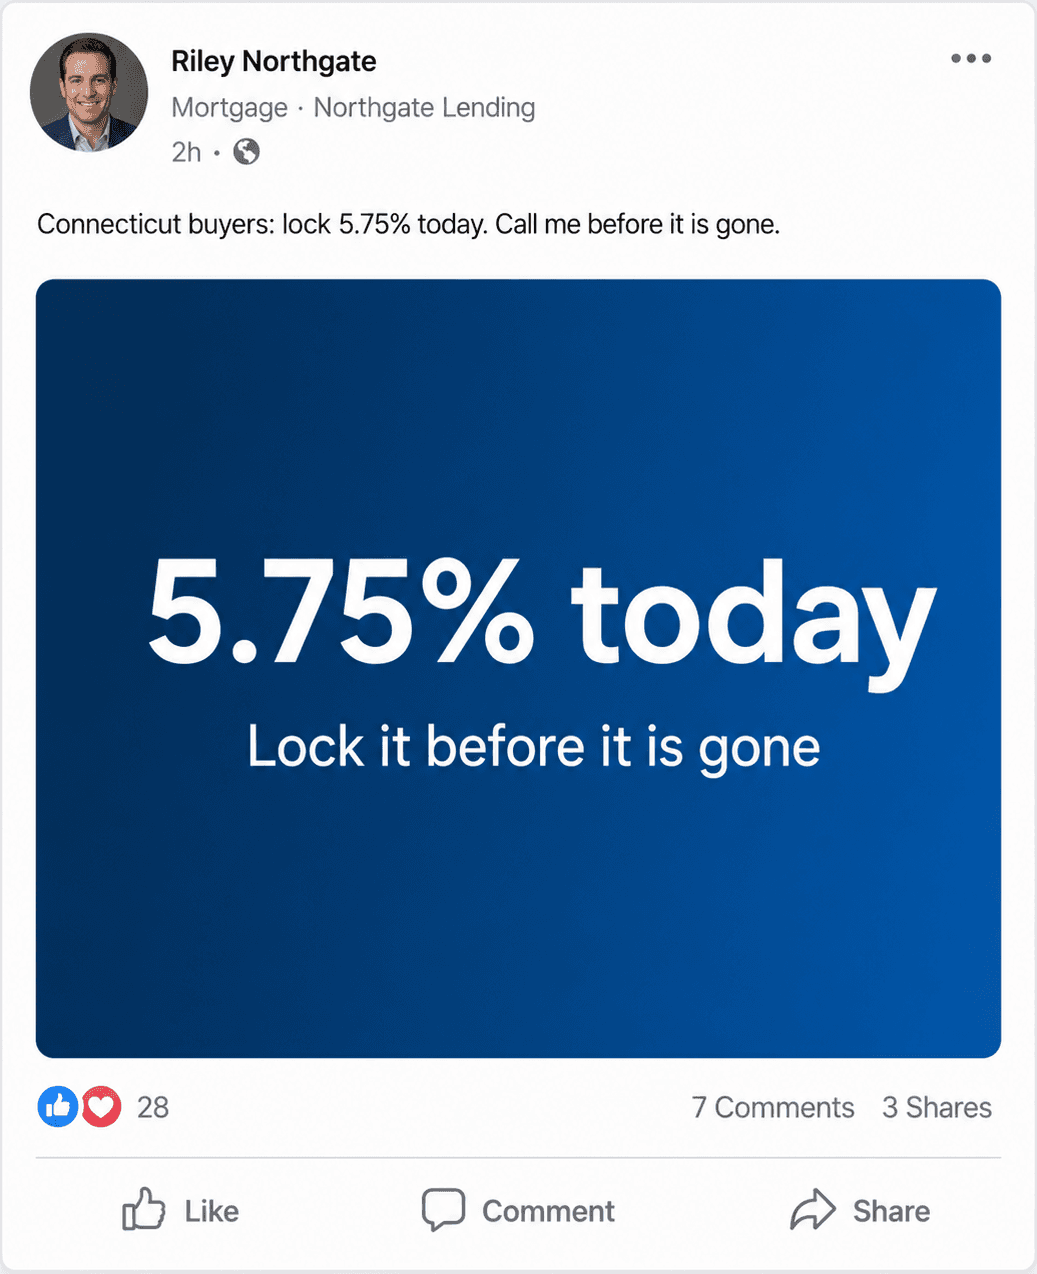
Conn. Gen. Stat. §36a-498e(5).
- Condition
- The post advertises a specific interest rate to Connecticut consumers. Connecticut prohibits advertising specific terms that are not actually available as offered at the time of the solicitation.
- Criteria
- Conn. Gen. Stat. §36a-498e(5).
A person subject to the Nondepository Mortgage Lenders and Brokers Act may not solicit, advertise or enter into a contract for specific interest rates, points or other financing terms unless the terms are actually available at the time of soliciting, advertising or contracting.
- Corrective action
- Only advertise rates and terms actually available as stated, with the required disclosures, or remove the specific rate.
We surface the accounts you are not watching
Compliance gaps hide on the profiles nobody flagged. Audit Hound follows the trail from your team's known pages and websites and pulls in the connected social properties they link to, so an account that never made it onto your roster still gets reviewed.
Regulators cite you for the account you were not watching. We bring it into view.
Reports show the evidence
Every finding names the exact rule, quotes the offending content, and includes the image of the post or profile where a picture is present, so the issue is documented, not just described. Reports are examiner-ready PDFs.
The process is the same for every review area: roster in, full-rulebook review, advisor confirmation, reports and tracked corrections out. See how it works, step by step
Every finding is confirmed by an EASE advisor before it reaches you. Sourced, human-reviewed reference, not legal advice.
One per company, officer, or trade name: the rule, the verbatim regulatory text, the evidence, and the fix. Built to hand to an examiner.
Drop an ad on Ask and it is reviewed against the same rulebook in seconds, so marketing can ask before they post.
Compliance, unleashed.
Transparent pricing from $149 per month, no demo required. Your first advisor-reviewed report arrives within a week of activation.